

NYC Real Estate Market Reports
Brooklyn Townhouse Report
2nd Quarter 2026
2Q Brooklyn Townhouse Report: At a glance
Brooklyn's townhouse market posted its strongest second quarter in years. Closed sales rose 35% year over year to 273, with multi-family townhouses leading at 200 closings, up 38%, and single-family homes recording 73 closings, up 28%. Median price rose 4% year over year to $2.43M. Average price climbed 5% to $3.098M. Average price per square foot crossed $1,000 for the first time, reaching $1,002, up 5% year over year. The demand that had been building through the first quarter translated into real closed activity at scale.
Volume Up Across Every Price Tier Above $1M.
The price range breakdown confirms this was not a narrow rally. Closings under $1M rose 83% year over year to 11, though the small base makes that figure less meaningful. The $1M to $2M band rose 19% to 81 closings. The $2M to $4M range, the core of Brooklyn's townhouse market, rose 40% to 126 closings, the strongest gain in that segment in several years. The over-$4M tier rose 45% to 55 closings. Demand was broad-based and present at every price point where inventory existed to meet it.
Single-Family: Average Price Up 16%, Price Per Square Foot Up 9%.
Single-family townhouses posted 73 closings, up 28% year over year. Median price rose 11% to $3.100M. Average price rose 16% to $4.395M. Average price per square foot rose 9% to $1,313. The jump in average price relative to median reflects a concentration of high-end sales pulling the average up — several significant transactions in Brooklyn Heights, Carroll Gardens, and Park Slope contributed meaningfully. Average square footage rose 7% to 3,348, suggesting buyers at the single-family level are finding and transacting on larger properties than a year ago.
Multi-Family: Volume Led the Quarter, Pricing Held Steady.
Multi-family townhouses drove the quarter's volume, posting 200 closings, up 38% year over year. Median price rose 2% to $2.200M and average price was essentially flat at $2.624M. Average price per square foot rose 3% to $875. The multi-family story in Q2 is primarily a volume story rather than a price appreciation story, with investors and owner-occupants both finding reasons to transact as inventory came to market. The Bed-Stuy, Crown Heights, and surrounding corridor dominated multi-family volume with 118 closings, up 42% year over year, confirming where the most active investment buyer pool is operating.
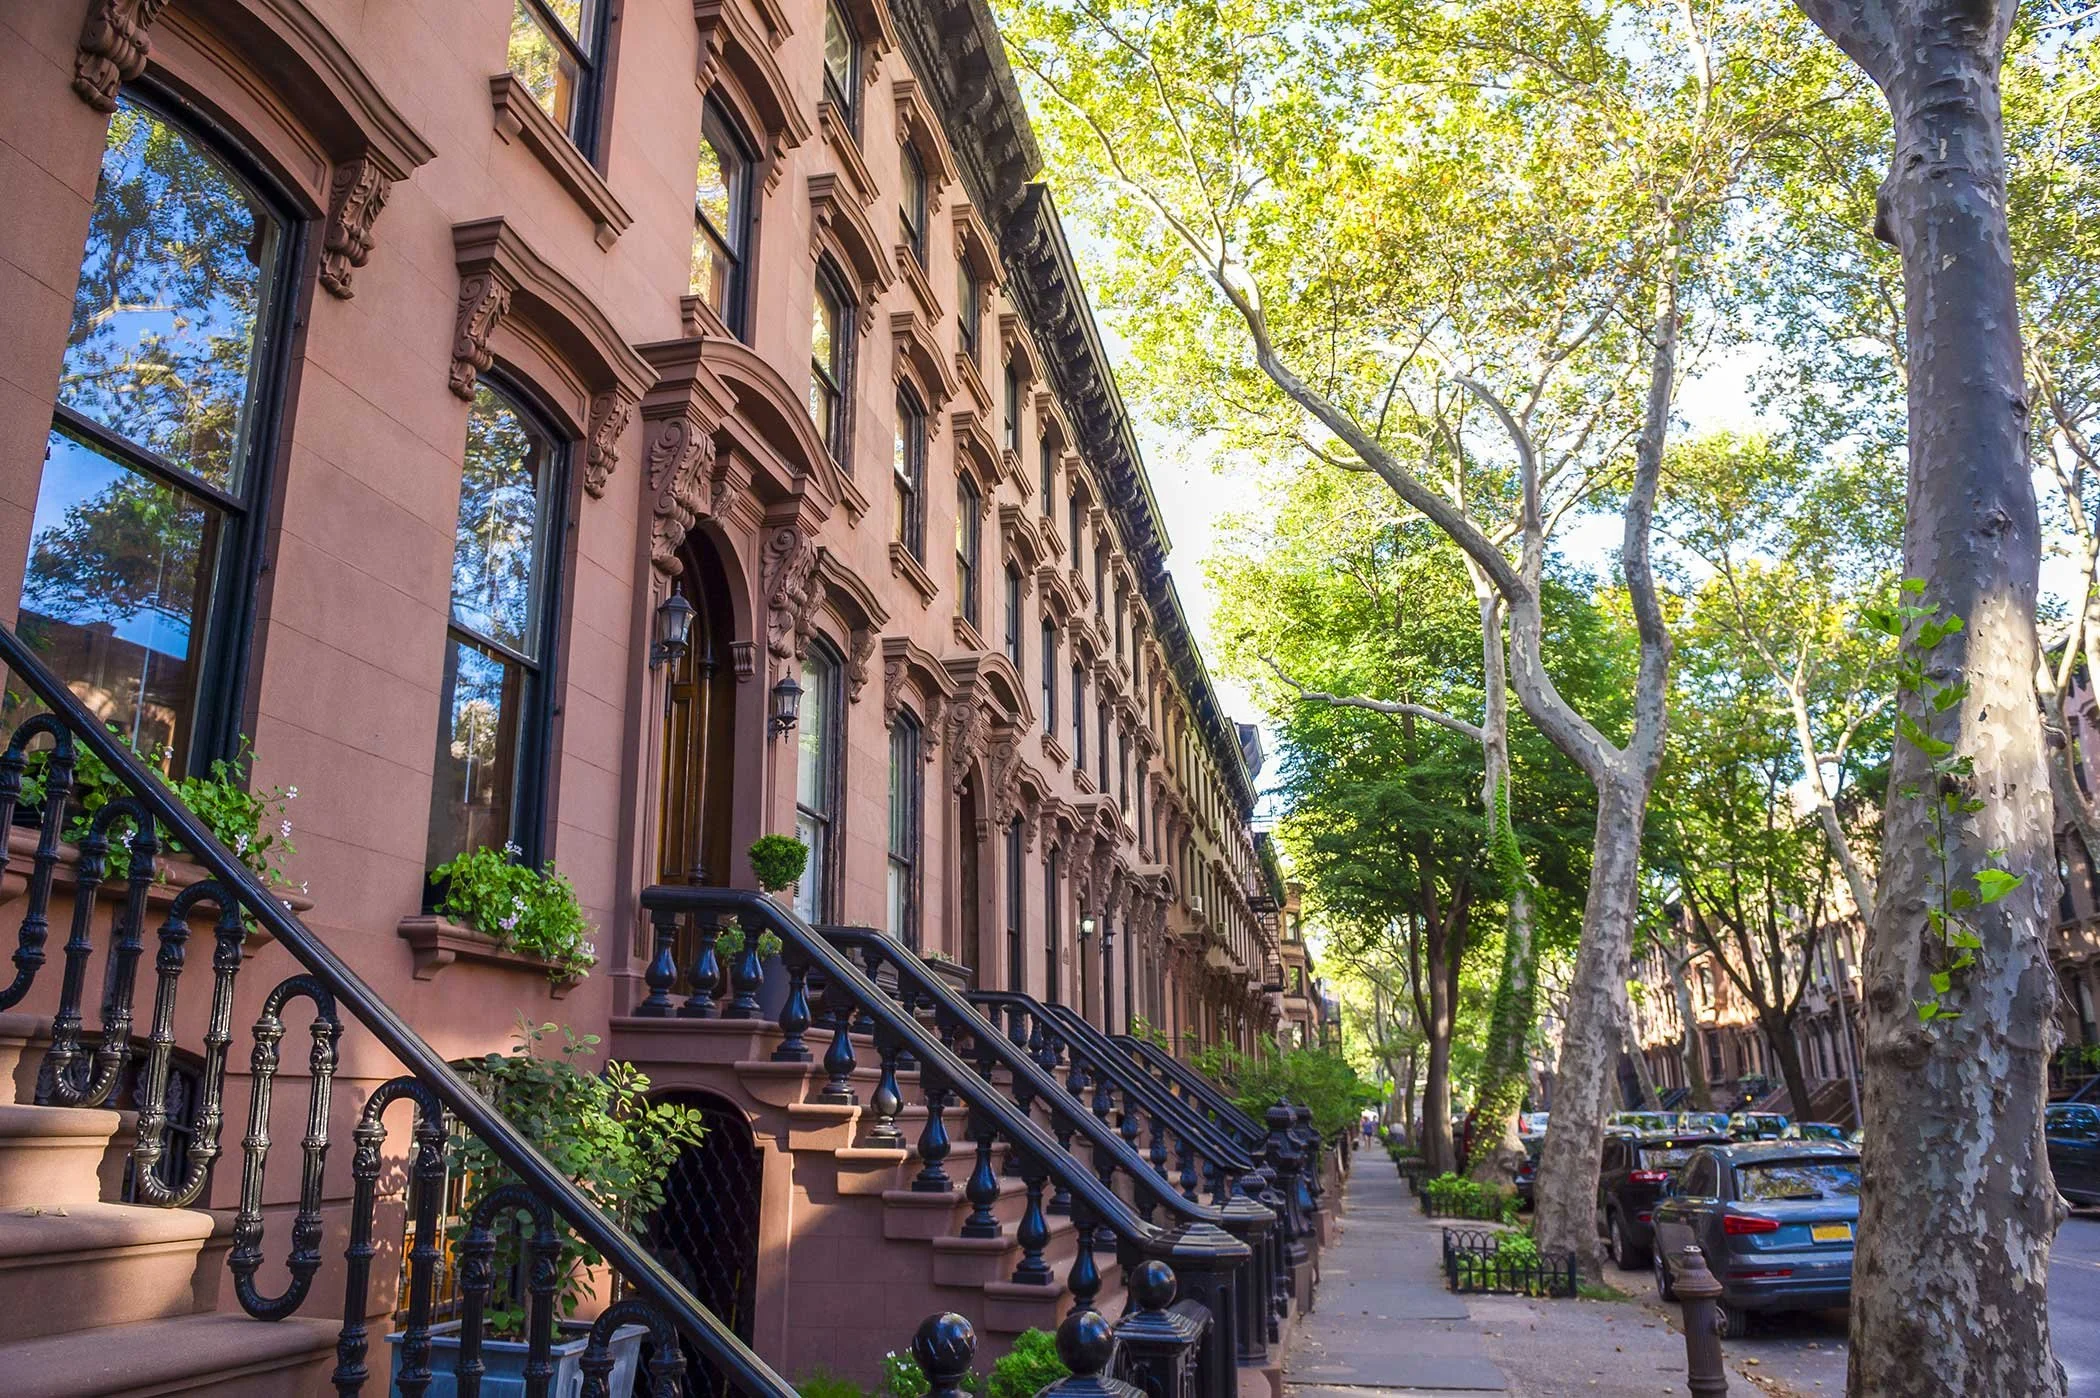
The Neighborhoods
Park Slope and Gowanus delivered the quarter's most striking single-family result. 13 closings, up 86% year over year. Median price rose 81% to $3.975M and average price rose 29% to $3.999M. Average price per square foot jumped 36% to $1,604, the highest in Brooklyn for single-family homes. The gains are partly compositional — a handful of significant transactions on premium blocks drove the average — but the direction is unambiguous. Park Slope single-family demand at the upper end is real and accelerating. On the multi-family side, 15 closings at a median of $2.800M with price per square foot up 9% to $1,120. The combination of compressed inventory and well-capitalized buyers produced the strongest single-family pricing of any submarket in the borough.
Carroll Gardens, Boerum Hill, and Red Hook was the multi-family standout of the quarter. 30 multi-family closings, up 76% year over year. Average price per square foot rose 19% to $1,300 and average price rose 9% to $4.186M. Single-family activity was also solid at 14 closings, up 40%, with median price rising 17% to $4.075M and average price per square foot up 17% to $1,443. This submarket consistently produces the second-highest price per square foot in Brooklyn for both product types, and Q2 reinforced that positioning. The buyers here are not cross-shopping with other neighborhoods. They are committed to this specific pocket of Brooklyn and willing to pay for it.
Brooklyn Heights, Cobble Hill, Dumbo, and Downtown remains in its own tier. 9 single-family closings at a median of $8.450M, up 14% year over year, and an average of $10.959M, up 19%. Average price per square foot of $1,985 is the highest in the borough and reflects the architectural scale and scarcity of what comes to market here. Average square footage of 5,520 per home is up 15% year over year. On the multi-family side, just 3 closings at a median of $9.995M, up 33%, with average price per square foot of $1,878. This submarket's transaction count will always be small. What trades here is significant regardless of volume.
Fort Greene, Clinton Hill, and Prospect Heights posted 7 single-family closings, up 17% year over year, with average price rising 27% to $4.529M. Multi-family was the more active story with 13 closings — down 32% year over year, though the Q1 comparison was unusually strong — at a median of $3.650M, up 22%, and average price per square foot of $1,154, up 8%. This submarket has one of the strongest price per square foot profiles in the borough for multi-family, reflecting the brownstone quality and location premium buyers are willing to pay.
Williamsburg and Greenpoint posted 3 single-family closings, up from 2 a year ago, with median price falling 28% on a small and volatile base. The multi-family story here was the quarter's most notable volume surge: 21 closings, up 110% year over year, at a median of $2.700M, up 17%, and average price per square foot of $963, up 5%. New development and investor activity in this corridor are contributing to the volume, and the doubling of multi-family closings in a single quarter reflects both pent-up demand and inventory that finally came to market.
Bedford-Stuyvesant, Crown Heights, Prospect Lefferts Gardens, and Bushwick is where Brooklyn's townhouse market actually lives at scale. 118 multi-family closings, up 42% year over year, the highest volume of any submarket by a wide margin. Median price fell 4% to $1.773M and average price was essentially flat at $1.901M. Price per square foot of $643, down 3%, reflects the market finding its level after several years of rapid appreciation in this corridor. This is not weakness — it is stabilization after a significant run. The 27 single-family closings, up 13%, at a median of $2.400M, up 18%, tell a different story: single-family demand in this corridor is growing and the prices are moving accordingly. For investors and buyers who want more space, more building, and more Brooklyn for their dollar, this remains the most active and accessible entry point into the townhouse market.
The Numbers That Matter Most
273 closings and a 35% annual gain is not a statistical artifact. It reflects buyers who were ready to act, inventory that came to market at competitive prices, and a product type that does not lose its appeal regardless of where rates are. Townhouses in Brooklyn are not rate-sensitive the way condos and co-ops are. The buyers pursuing them have made a deliberate decision about how they want to live, and they are competing for a finite supply of properties that cannot be replicated or replaced.
The crossing of $1,000 per square foot in average pricing is worth noting. That threshold has served as a ceiling for stretches of the past several years. Clearing it, even by a modest margin, signals that the buyer pool at the upper end of the market is willing to pay more than the historical floor suggested. Whether that holds in the second half of the year depends on inventory more than demand. The demand is there. The question is always what comes to market for it to compete over.
For sellers: Q2 data makes the case. Buyers are active, prices are at or near record levels in most submarkets, and the over-$4M tier posted a 45% gain in closings. A well-presented, correctly priced townhouse in any of the core Brownstone Brooklyn neighborhoods is not sitting. The listings accumulating days on market are not there because buyers have lost interest. They are there because pricing has not met the market.
For buyers: volume was up 35% in Q2, which means more was available to buy. That created opportunity. The fall market will bring another cycle of new listings. A buyer who is prepared, with financing confirmed and an understanding of what they actually want and what they can realistically expect to pay, is positioned to move when the right property appears.

Buying or Selling a Brooklyn Townhouse?
The townhouse market requires a different analysis than condos or co-ops. If you are thinking about a house in Brooklyn, I am happy to give you a clear read on what the current market looks like for your specific situation.